One of the biggest questions people have when buying health insurance is:
“I already have a health condition. Will my insurance cover its treatment?”
The answer is possibly yes, but usually not immediately.
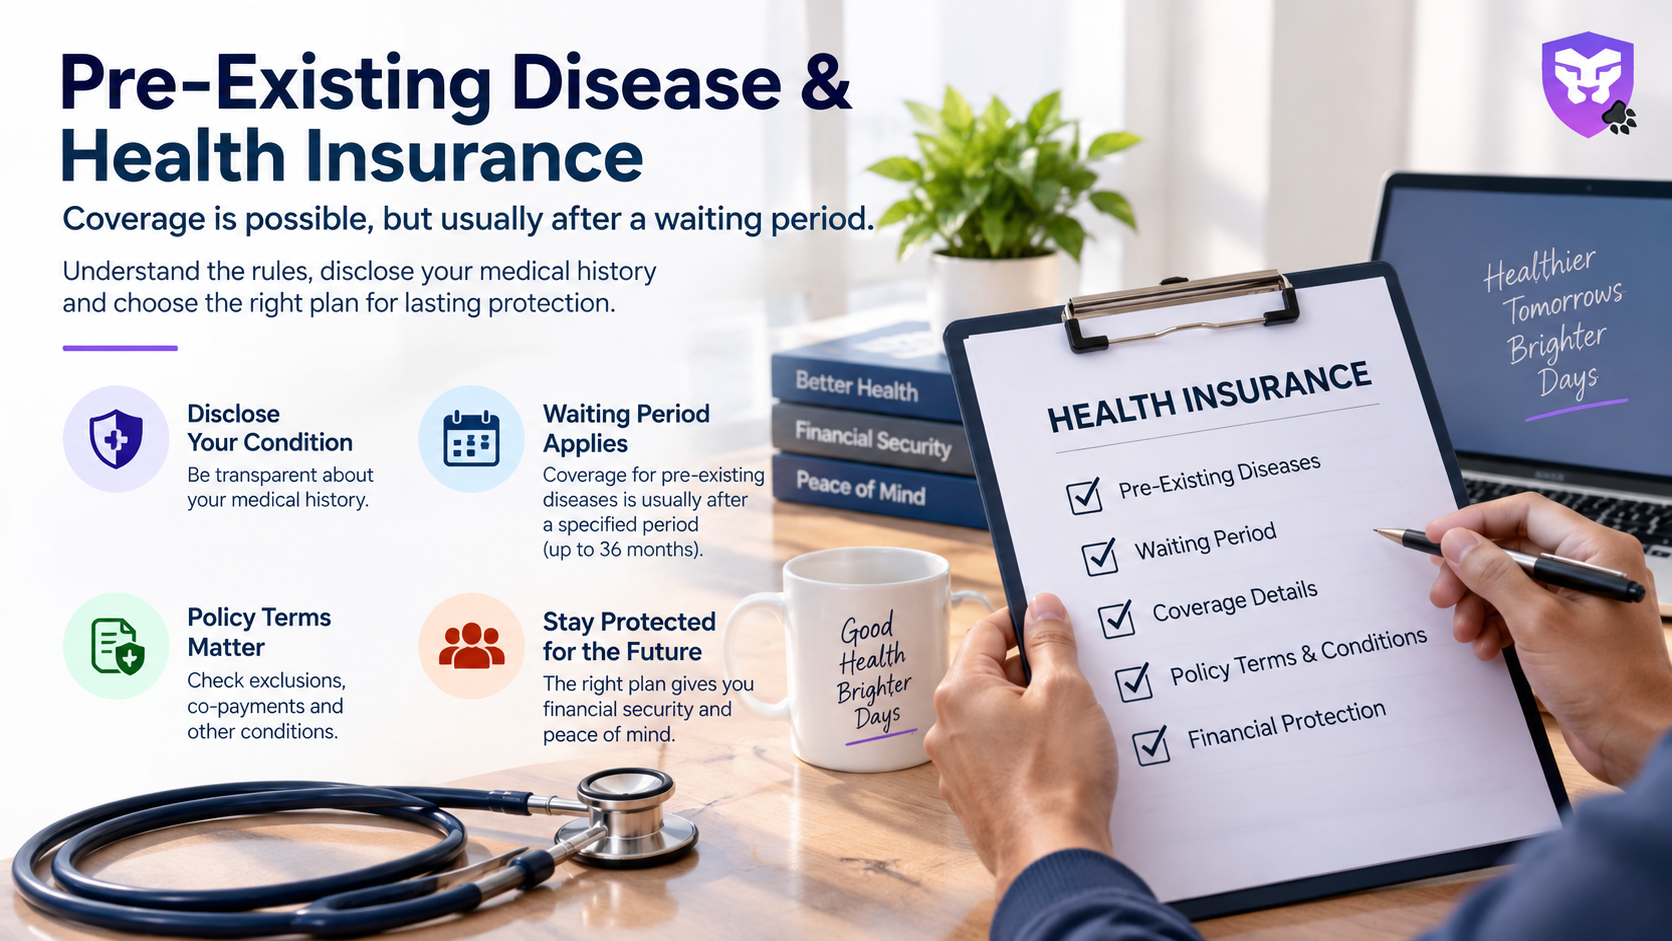
A health condition that existed before you purchased the policy may be treated as a pre-existing disease (PED) under the policy and may be subject to a waiting period before related treatment is covered.
The exact definition and terms depend on the applicable regulations and the policy wording. Under the current IRDAI framework, a pre-existing disease generally refers to a condition, ailment, injury or disease that was diagnosed, or for which medical advice or treatment was recommended or received, within the specified period before the policy starts. IRDAI's current information states a maximum PED waiting period of 36 months of continuous coverage for health insurance policies.
That does not mean every policy makes you wait 36 months. An insurer may offer a shorter waiting period depending on its product design.
The important point is to understand what is covered, what is waiting, what you need to disclose and when the waiting period begins.
Quick Answer: Will Health Insurance Cover a Pre-Existing Disease?
Yes, a pre-existing disease can be covered by health insurance, but coverage is generally subject to the policy's waiting period, underwriting decision and terms and conditions.
Under the current IRDAI framework, the waiting period for disclosed pre-existing diseases can be up to 36 months of continuous coverage. Insurers may offer shorter waiting periods depending on the policy.
For example, if a policy has a 2-year waiting period for pre-existing diseases, treatment related to the covered pre-existing condition would generally become eligible after the applicable waiting period is completed, subject to the policy terms and continuous coverage.
However, simply having the disease listed on your application does not automatically guarantee that every related expense will be paid. The insurer's acceptance, policy wording, exclusions, sub-limits, co-payment and other conditions still matter.
What Is a Pre-Existing Disease in Health Insurance?
A pre-existing disease is a medical condition that existed before the health insurance policy began and falls within the applicable definition under the insurance policy and regulatory framework.
IRDAI's current health-insurance information describes PED in terms of a condition, ailment, injury or disease diagnosed by a physician, or for which medical advice or treatment was recommended or received, within the specified period before policy commencement.
Examples may include conditions such as:
- Diabetes
- Hypertension
- Asthma
- Thyroid disorders
- Heart disease
- Certain chronic illnesses
- Previous major medical conditions
Whether a specific condition is treated as a PED depends on the facts, medical history, policy wording and applicable definition.
Why does PED status matter?
This distinction is important because insurers use medical and other information to assess the risk they are agreeing to cover.
A pre-existing disease may therefore have:
- A waiting period
- Specific exclusions
- Additional policy conditions
- Co-payment requirements
- Other product-specific restrictions
These details should be checked before purchasing the policy.
What Is the Waiting Period for a Pre-Existing Disease?
A waiting period is the period during which a specified condition or treatment is not covered under the policy.
For pre-existing diseases, IRDAI's current health-insurance information states that the maximum waiting period is up to 36 months. The 2024 IRDAI Insurance Products Regulations similarly state that the waiting period for disclosed PEDs can be a maximum of 36 months of continuous coverage.
The key word is maximum.
Your particular policy may have a shorter waiting period.
For example:
| Policy PED Waiting Period | General Meaning |
|---|---|
| 1 year | PED-related treatment may become eligible after the applicable 1-year waiting period. |
| 2 years | PED-related treatment may become eligible after the applicable 2-year waiting period. |
| 3 years | PED-related treatment may become eligible after the applicable 3-year waiting period. |
The exact claim eligibility remains subject to the policy terms.
When Does the Pre-Existing Disease Waiting Period Start?
In general, the waiting period starts from the commencement of the applicable health insurance coverage, as per the policy terms.
The important factor is continuous coverage.
IRDAI's health-insurance information states that waiting periods apply from commencement and that the benefit after completion of the applicable period depends on the policy being continuously renewed without a break.
Example
Suppose you purchase a health insurance policy on 1 April 2026.
and the policy has the following:
2-year PED waiting period
The relevant waiting period would generally run from the policy commencement date, subject to the policy's terms and continued renewal.
The exact date on which a particular claim becomes eligible should always be confirmed in the policy schedule and wording.
Does This Mean My Entire Health Insurance Is Not Active?
No.
A PED waiting period does not necessarily mean that your entire health insurance policy is inactive.
It generally means that treatment related to the specified pre-existing disease may not be covered during the applicable waiting period.
Other illnesses, injuries or treatments may be covered according to the policy, subject to applicable waiting periods and exclusions.
For example, someone with diabetes may purchase health insurance and have diabetes-related treatment subject to the PED waiting period, while an unrelated covered medical event may be assessed under the policy's other terms.
This scenario is why it is important to distinguish between:
“My policy is active."
and
“Every medical condition is immediately covered.”
They are not the same thing.
Confused between health insurance plans?
Let AI decide for you.
- AI compares 30+ insurers
- No sales pressure
- Result in 60 seconds
- 100% free
No spam. No calls unless you want them.
What Happens After the Waiting Period Ends?
Once the applicable PED waiting period is completed, treatment related to the pre-existing condition may become eligible for coverage, subject to the policy terms.
This can include eligible hospitalisation or other covered treatment, depending on the product.
However, you should still check:
- Exclusions
- Sub-limits
- Co-payment
- Room-rent restrictions
- Deductibles
- Treatment-specific conditions
- Coverage limits
- Network hospital requirements
- Claim documentation
Completing the PED waiting period does not mean every expense connected to the condition is automatically payable.
Why Is It Important to Declare Your Existing Disease?
Never hide or deliberately misrepresent your medical history when purchasing health insurance.
When applying for a policy, provide accurate information about relevant diagnoses, treatment and medical advice.
IRDAI's framework recognises disclosure and underwriting as key aspects of health insurance. The 2024 Insurance Products Regulations also state that insurers should endeavour to offer products for people with existing medical conditions.
Accurate disclosure helps the insurer evaluate the proposal and helps you understand the coverage before a claim occurs.
What could happen if you do not disclose a condition?
If a relevant condition is not properly disclosed, it can create disputes or complications during claim assessment.
That is why providing complete and truthful information is one of the most important steps when purchasing health insurance.
Does Every Insurance Company Cover Pre-Existing Diseases?
Not necessarily in the same way.
Insurers can design products based on their underwriting policies and product structure. IRDAI specifically notes that offering coverage to people with existing illnesses is subject to the insurer's underwriting policy and product design.
One policy may offer:
3-year PED waiting period
while another may provide a shorter waiting period.
Other differences may include:
- Premium
- Coverage limits
- Disease-specific exclusions
- Co-payment
- Network hospitals
- Restoration benefits
- Room-rent conditions
- Claim procedures
Therefore, do not compare policies only by premium.
Can I Buy Health Insurance If I Already Have a Disease?
Yes, health insurance can be available to people with existing medical conditions, but acceptance and terms depend on the insurer and product.
IRDAI's 2024 Insurance Products Regulations state that insurers should endeavour to offer coverage for people with all types of existing medical conditions, while actual underwriting and product terms still apply.
Depending on the policy, the insurer may:
- Accept the proposal
- Apply a waiting period
- Apply other policy conditions
- Offer a product specifically designed for certain health profiles
- Underwrite the applicant based on the disclosed medical information
This is why comparing multiple health insurance plans can be useful.
What Diseases Can Have a Waiting Period?
There is no universal list that means every insurer treats every disease identically.
The applicable PED waiting period depends on:
- Your medical history
- The insurer
- The policy
- Product design
- Underwriting
- Applicable regulations
Common examples of conditions that may be treated as pre-existing include:
- Diabetes
- Hypertension
- Asthma
- Thyroid conditions
- Heart conditions
- Chronic respiratory conditions
The exact classification should be confirmed from the insurer's policy wording rather than assumed.
What Is the Difference Between PED Waiting Period and Initial Waiting Period?
These two concepts are often confused.
PED Waiting Period
This period applies specifically to conditions treated as pre-existing diseases under the policy.
Initial Waiting Period
A new health insurance policy can also have an initial waiting period for illnesses generally. IRDAI's health-insurance information states that a general waiting period can apply at the beginning of a new policy, with accident-related hospitalisation treated differently under the applicable rules.
Why does this matter?
Suppose someone already has hypertension and buys a new policy.
There could be:
A PED waiting period for hypertension
and separately:
An initial waiting period applicable to certain new illnesses
Both should be understood before purchasing the policy.
Confused between health insurance plans?
Let AI decide for you.
- AI compares 30+ insurers
- No sales pressure
- Result in 60 seconds
- 100% free
No spam. No calls unless you want them.
What Happens If I Increase My Sum Insured Later?
An increase in coverage can have different treatment under the policy terms.
For some policy structures, waiting periods may apply afresh to the increased portion of the sum insured.
This means you should not assume that increasing a policy from ₹10 lakh to ₹20 lakh automatically gives the entire additional amount immediate coverage for every condition.
Always check the policy wording before increasing your coverage.
Can Portability Help With a Pre-Existing Disease Waiting Period?
Health insurance portability can be important when you already have continuous health insurance coverage.
IRDAI's current health-insurance framework provides portability arrangements, and you can carry over applicable waiting-period credit according to the regulatory and policy conditions.
This means you should not automatically assume that switching insurers means starting every waiting period from zero.
The exact credit depends on factors such as:
- Existing coverage
- Continuous coverage
- Sum insured
- Portability rules
- New policy terms
Before switching, compare the existing policy and the new policy carefully.
What If My Health Insurance Policy Has a Break?
Continuous coverage is important for waiting-period benefits.
IRDAI states that coverage after the applicable waiting period is linked to continuous renewal without a break.
A break in policy coverage can therefore have serious consequences for continuity-related benefits.
Practical tip
Make sure you renew your health insurance well before the renewal date.
Set a reminder before the renewal date and understand the applicable grace period and continuity rules in your policy.
Can I Claim for a Different Illness During the PED Waiting Period?
Potentially, yes, depending on the policy.
A PED waiting period generally relates to the pre-existing condition and its applicable treatment. It does not necessarily mean that no health claim can be made for every other covered medical event.
However, other waiting periods and exclusions may also apply.
For example:
- PED treatment may be waiting
- Certain listed procedures may have another waiting period
- A new illness may be covered subject to the policy's initial waiting period
- Accident-related treatment may follow separate provisions
Always check the policy wording for the exact situation.
Does Health Insurance Cover Complications of a Pre-Existing Disease?
A complication directly related to a pre-existing condition may also be subject to the PED waiting period and policy terms.
For example, if a policy treats a particular diabetes condition as pre-existing, complications directly related to that condition may not automatically become payable before the applicable waiting period ends.
The exact claim decision depends on the medical facts and policy wording.
How to Choose Health Insurance When You Have a Pre-Existing Disease
If you already have a medical condition, do not choose a policy based on premium alone.
Check these factors carefully:
1. PED Waiting Period
A shorter waiting period can be valuable, provided the overall policy remains suitable.
2. Coverage Amount
Make sure the sum insured is appropriate for your age, family and expected healthcare needs.
3. Co-Payment
Check whether you are required to bear a percentage of eligible medical expenses.
4. Disease-Specific Conditions
Look for treatment-specific limits or exclusions.
5. Network Hospitals
Choose a policy with hospitals that are accessible and relevant to you.
6. Claim Process
Understand how to notify and document a claim.
7. Renewal Terms
Long-term continuity is particularly important when waiting-period credits and ongoing health coverage are involved.
A Simple Example
Imagine that Rahul has hypertension and wants to purchase health insurance.
He applies for a ₹10 lakh policy and fully discloses his condition.
Confused between health insurance plans?
Let AI decide for you.
- AI compares 30+ insurers
- No sales pressure
- Result in 60 seconds
- 100% free
No spam. No calls unless you want them.
The insurer accepts the proposal with a 2-year waiting period for pre-existing diseases.
In this situation:
Year 1:
Hypertension-related treatment may generally remain subject to the PED waiting period.
Year 2:
The waiting period is still being completed.
After the applicable 2-year period:
Eligible hypertension-related treatment may become covered, subject to the policy's terms.
Rahul must still check exclusions, co-payment, sub-limits and other policy conditions.
This is why the waiting period printed in the actual policy matters more than a general assumption.
Common Mistakes to Avoid
Assuming Every Existing Disease Is Permanently Excluded
A pre-existing disease may be covered after the applicable waiting period if the insurer has accepted it under the policy terms.
Choosing Only on the Basis of Premium
The cheapest policy may have restrictions that are unsuitable for your medical needs.
Hiding Medical Information
Incomplete disclosure can create claim-related problems.
Ignoring the Waiting Period
Always check the exact PED waiting period before buying.
Forgetting About Continuity
A policy should be renewed on time to maintain continuous coverage.
Checking Only the Sum Insured
While ₹10 lakh coverage may seem attractive, the policy's exclusions and conditions are equally important.
Frequently Asked Questions
Will health insurance cover my pre-existing disease?
Yes, a pre-existing disease can be covered after the applicable waiting period if the insurer accepts the condition under the policy. The exact coverage depends on the policy wording and terms. IRDAI's current framework allows a maximum PED waiting period of 36 months.
How long is the waiting period for pre-existing diseases?
The maximum waiting period for disclosed PEDs is up to 36 months of continuous coverage under the current IRDAI framework. Individual policies may offer a shorter waiting period.
Can I get health insurance if I have diabetes?
Yes, people with diabetes may be able to obtain health insurance, subject to the insurer's underwriting and product terms. Diabetes may be treated as a pre-existing disease depending on the facts and applicable policy definition.
Can I get health insurance if I have high blood pressure?
Yes. Hypertension does not automatically mean that you cannot obtain health insurance. However, the insurer may apply a PED waiting period or other policy conditions.
Can I buy health insurance after being diagnosed with a disease?
You may still be able to buy health insurance after diagnosis, although the condition may be treated as pre-existing and subject to underwriting and a waiting period.
Does the PED waiting period start from the date I was diagnosed?
Not necessarily. The waiting period under the health insurance policy generally runs from the policy commencement date, subject to the policy terms. The diagnosis date is relevant to determining whether a condition qualifies as pre-existing.
Can I switch health insurance companies with a pre-existing disease?
Yes, portability may be possible. Applicable waiting-period credit can carry over according to IRDAI portability rules and the conditions of the new policy.
Will my existing disease affect my health insurance premium?
It can. Premiums and policy terms may depend on the insurer's underwriting approach, age, product design and other risk factors.
Can my pre-existing disease ever be permanently excluded?
Depending on the policy and applicable framework, certain existing diseases may be subject to specific exclusions or conditions. IRDAI notes that some disclosed existing diseases can be permanently excluded under applicable standardised exclusion rules.
Final Thoughts
Having a pre-existing disease does not automatically mean that you cannot get health insurance or that your condition will never be covered.
The more important questions are:
Has the insurer accepted the condition?
What is the PED waiting period?
What happens after the waiting period?
Are there any exclusions, co-payments or sub-limits?
Under the current IRDAI framework, the maximum waiting period for disclosed pre-existing diseases is up to 36 months of continuous coverage, although individual insurers may offer shorter periods.
For anyone buying health insurance with an existing medical condition, transparency is essential. Disclose your medical history accurately, read the policy wording carefully, compare waiting periods and understand the claim conditions before purchasing.
The best health insurance is not simply the policy that accepts you. It is the policy whose coverage, waiting period, exclusions and terms you understand and can rely on when you need medical care.

Written By
Raj Shankar
Principal Officer and General Manager at CoverTiger
With over 7 years of experience in the insurance and fintech industry, Raj Shankar has helped 10,000+ customers secure their families with the right insurance solutions. He has worked with leading brands such as Policybazaar, INDmoney, and CoverTiger, building strong expertise in health insurance, life insurance, sales leadership, and customer advisory. His mission is to make insurance simpler, more transparent, and accessible for every Indian family.